An interest rate swap (IRS) is a financial derivative instrument that involves an exchange of a fixed interest rate for a floating interest rate. More specifically,
An interest rate swap’s (IRS’s) effective description is a derivative contract, agreed between two counterparties, which specifies the nature of an exchange of payments benchmarked against an interest rate index. The most common IRS is a fixed for floating swap, whereby one party will make payments to the other based on an initially agreed fixed rate of interest, to receive back payments based on a floating interest rate index. Each of these series of payments is termed a ‘leg’, so a typical IRS has both a fixed and a floating leg. The floating index is commonly an interbank offered rate (IBOR) of specific tenor in the appropriate currency of the IRS, for example LIBOR in USD, GBP, EURIBOR in EUR or STIBOR in SEK. To completely determine any IRS a number of parameters must be specified for each leg; the notional principal amount (or varying notional schedule), the start and end dates and date scheduling, the fixed rate, the chosen floating interest rate index tenor, and day count conventions for interest calculations. Read more
The above description refers to a plain vanilla interest rate swap. However, interest rate swaps can come in many different flavors. These include, (but are not limited to)
- Amortizing notional IRS
- Cross-currency swap
- Float-for-float (basis) swap
- Overnight index swap
- Inflation swap etc.
Interest rate swaps are often used to hedge the fluctuation in the interest rate. To value an interest rate swap, fixed and floating legs are priced separately using the discounted cash flow approach.
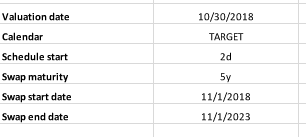
Below is an example of a hypothetical plain vanilla interest rate swap
Maturity: 5 years
Notional: 10 Million EUR
Fixed rate: 3.5%
Floating rate: Euribor
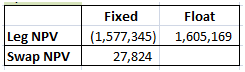
The values of the fixed, floating legs and the interest rate swap are calculated using an Excel spreadsheet. Table below presents their values
Related article: Interest Rate Swap-Derivative Pricing in Python
To download the accompanying Excel workbook or Python program for this post:
1. Subscribe to the newsletter. If you're already a subscriber, go to the next step
2. Once subscribed, wait for the next newsletter where you can find a link for referring a friend. Use that link to refer a friend or two
After completing these steps, you’ll gain access to the file for this post, along with files for a dozen other posts.
Further questions
What's your question? Ask it in the discussion forum
Have an answer to the questions below? Post it here or in the forum


THANKS FOR SHARING
GOOD!
good stuff
Nice explanation